When you sell
More available lenders can give buyers more ways to finance a purchase. Hutton’s commitment is a financeable condominium: Fannie Mae approval where the project qualifies, and other lender options where it does not.
Explore what a condominium deed could change: your home’s value, your financing choices, and how your community pays for needed work.
The benefits depend on your building. Here is what to consider, with examples from communities that have converted.
Request your free feasibility studyA buyer needs more than a home they like. They usually need a lender willing to finance it. When few lenders serve a cooperative, the pool of buyers who can complete a purchase can be smaller.
Condominium ownership can broaden those financing possibilities. That can change the market for the same home, in the same building.
It is a reason to examine conversion—not a promise of appreciation. Location, condition and the market still matter.
Deferred maintenance affects the building you live in today and the home you may sell tomorrow. Conversion can be an occasion to address the underlying mortgage and arrange financing for capital work together.
The money has to come from somewhere. A sound plan explains what will be funded, who will repay the financing and what owners will owe afterward.
Read the Mountain Club case studyMountain Club · New Jersey
$2.5 million
The community had deferred maintenance to address. Its 2005 conversion included funding for building work.
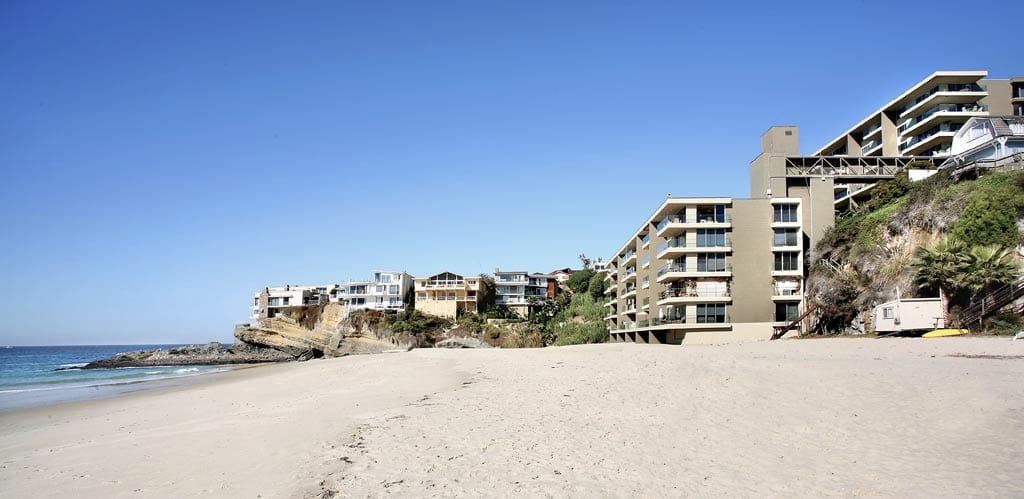
A land lease can leave owners facing rent increases or uncertainty about the future of the property.
At Laguna Lido, conversion included purchasing the land. Each deed holder took a proportionate share of that purchase. The change addressed ownership of the land as well as the homes.
For another community, the possibilities depend on its lease and the terms of a purchase.
Explore Laguna LidoWith a condominium, financing is tied to your deeded unit. That can open options that are difficult to find for a cooperative share.
More available lenders can give buyers more ways to finance a purchase. Hutton’s commitment is a financeable condominium: Fannie Mae approval where the project qualifies, and other lender options where it does not.
Refinancing or an equity loan can make it possible to use part of your home’s value without selling it. You still need to qualify, and the amount borrowed must be repaid.
For eligible owners, Hutton can arrange access to reverse mortgages, often at conversion closing. That access is very uncommon for co-op shareholders today. The owner, property and loan must meet the lender’s requirements.
Start with the financing possibilities for your own building.
A deed puts your unit in your name as real property. That matters when you decide to sell, borrow against the home, place it in a trust or leave it to your heirs.
Your estate plan can address the condominium directly, with transfer requirements set out in the governing documents and applicable law.
The association still has a job to do. Common areas, shared services, insurance and reserves continue to need management and funding.
Conversion is an opportunity to update the documents your community lives by. We prepare the new condominium documents around the owners’ decisions, retaining existing rules where appropriate and revising provisions that need to change.
The board and management can continue if that is the community’s choice. The documents must also meet applicable law and financing requirements.
What this means for your boardThe condominium documents we prepare provide for:
These are provisions we prepare in the conversion documents, not automatic features of every condominium.
A free feasibility study examines your cooperative’s unit values, existing debt, financing and conversion expenses. You and your neighbors can then weigh a specific proposal for the building you actually own.
Or write to info@huttonfirm.com.